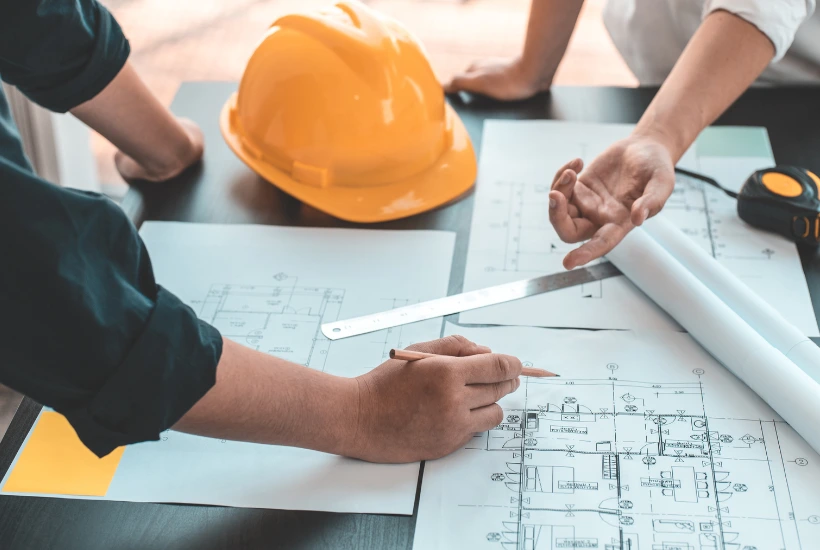
Florida’s construction industry faces a mix of risks that most other states simply don’t see: hurricane-force storms, year-round outdoor labor in extreme heat, and a legal environment that holds contractors to strict liability standards. One lapse in coverage can undo years of work overnight.
So if you run a construction business in Florida, knowing what are the top protection priorities for Florida construction businesses isn’t optional – it’s the foundation of staying solvent. Here are five coverage areas every contractor in the state should have locked down.
General Liability Insurance
Every solid approach to risk protection for Florida contractors starts with general liability – the policy that covers property damage and bodily injury claims that arise from your operations.
Without it, a single lawsuit from a client, a property owner, or a bystander could cost more than your annual revenue. General liability is also the coverage most project owners and general contractors require before you step onto their job site, so it’s not just financial protection – it’s effectively your entry ticket to bid on work.
Florida courts tend to side with claimants in construction disputes, and litigation costs run steep. A policy with solid per-occurrence and aggregate limits gives you the financial backing to defend a claim, cover a settlement, or absorb a judgment without draining your business accounts.
Most small contractors carry $1 million per occurrence as a floor, but projects in high-value markets – Miami, Tampa, or anywhere along the Gulf Coast – often push subcontractors toward higher limits before work can begin.
Workers’ Compensation Coverage
Florida law mandates workers’ compensation insurance for any construction business with one or more employees, and the state enforces that requirement more aggressively than most.
The Florida Division of Workers’ Compensation runs regular stop-work order operations at active job sites. A violation can trigger a fine equal to twice the premiums you’d have paid over the prior two years, not something you want to absorb mid-project with payroll still coming due.
Beyond the legal requirement, the practical need is straightforward. Construction is physically demanding. Falls from heights, equipment injuries, and heat-related illness are regular occurrences on Florida job sites, especially through the long summer months. Workers’ comp pays for medical treatment and wage replacement when an employee gets hurt, which keeps your crew taken care of and keeps you out of civil court.
The catch is that Florida’s construction workers’ comp rates are partly determined by job classification and your experience modification factor – so a strong safety record directly lowers your premiums over time, which makes safety investment a financial decision as much as an ethical one.
Builder’s Risk Insurance
Builder’s risk insurance covers a structure under construction against physical damage from fire, theft, vandalism, and certain weather events before the project reaches completion.
In Florida, this policy is non-negotiable. The state sees more named storms and severe weather events than almost anywhere else in the country, and an uninsured loss mid-project can leave you financially on the hook for rebuilding a structure you haven’t yet been paid to finish.
Most lenders and project owners require builder’s risk as a condition of financing or contract execution. It typically covers the structure itself, materials stored on-site, and sometimes materials in transit; but coverage terms vary widely between carriers, so read the exclusions before you sign anything.
Standard builder’s risk policies often exclude flood damage, which matters enormously in low-lying Florida markets. A separate flood endorsement may well be worth the added cost, particularly for projects near the coast or inside FEMA-designated flood zones where storm surge is a genuine threat.
Commercial Auto Insurance
If your business operates trucks, vans, or any vehicle used to haul equipment, transport crews, or travel between job sites, personal auto insurance won’t cover an accident that occurs during work hours.
Florida requires commercial auto coverage for vehicles used in business operations, and a gap here can expose you personally to a six-figure liability claim after a single traffic accident.
Florida’s roads carry heavy construction traffic, and the state has one of the higher uninsured motorist rates in the country. If one of your drivers gets hit by someone without coverage, you need your own policy to absorb the damages.
Commercial auto policies for contractors typically include liability, collision, full coverage, and uninsured motorist protection. For fleets of three or more vehicles, a fleet policy can simplify administration and often cuts the per-vehicle cost.
Don’t overlook hired-and-non-owned auto coverage either, if your employees ever use personal vehicles for company errands or site runs, that exposure needs to be addressed.
Tools and Equipment Coverage
Your tools and equipment represent serious capital, and they’re among the most theft-prone assets on any job site. Standard general liability policies don’t cover your own property, they only respond to damage or injury you cause others.
Tools and equipment coverage fills that gap, paying to repair or replace gear that gets stolen, damaged, or destroyed during a project.
Job site theft in Florida runs higher in urban markets and during periods of rapid construction activity. Replacing a high-end generator, a laser level, or a specialty trade tool out of pocket can stall a project and squeeze cash flow hard.
These policies can cover items on-site, in transit, and at your storage facility, though limits and deductibles vary by carrier. Larger contractors may need inland marine insurance for equipment valued above standard tools-floater thresholds.
And if you lease any equipment, check whether your lease agreement specifies coverage at particular values, many do, and an undercovered loss can spark a contract dispute on top of the equipment loss itself.
Conclusion
The top protection priorities for Florida construction businesses share a common thread: each one targets a real, high-probability risk that the state’s environment, legal system, and industry norms make worse than average. General liability and workers’ comp form the legal and financial baseline.
Builder’s risk, commercial auto, and tools coverage protect the physical assets that keep your business running day to day. Get all five in place – and revisit them annually as your revenue and project scope grow – so that one bad event doesn’t become a permanent setback.
Related posts:
Smart Home Improvements That Boost Comfort and Energy Efficiency
Why Investing in Insulation Saves Money and Energy
The Benefits of Investing in Durable Exterior Home Upgrades
From Chaos to Calm: Design a Mudroom Your Pets Will Love
How to Use Playmats & Rugs in Modern Dining Setup
How Pressure Washing Extends the Life of Your Driveway and Siding
- What Are the Top Protection Priorities for Florida Construction Businesses - September 19, 2026
- How to Design a Timber Frame Interior That Feels Modern: 5 Fixes for Too Much Wood - September 17, 2026
- The Best Omegle Alternatives in 2026 - September 15, 2026
Leave a Reply